Fuel Switch Snapshot: LBM nips at LSMGO’s heels in Rotterdam
Rotterdam LBM’s discounts to LSMGO narrow to $17-137/mt
LBM costs more than HSFO, VLSFO and B100 in Rotterdam
Rotterdam’s B100 flips to $26/mt premium over HSFO
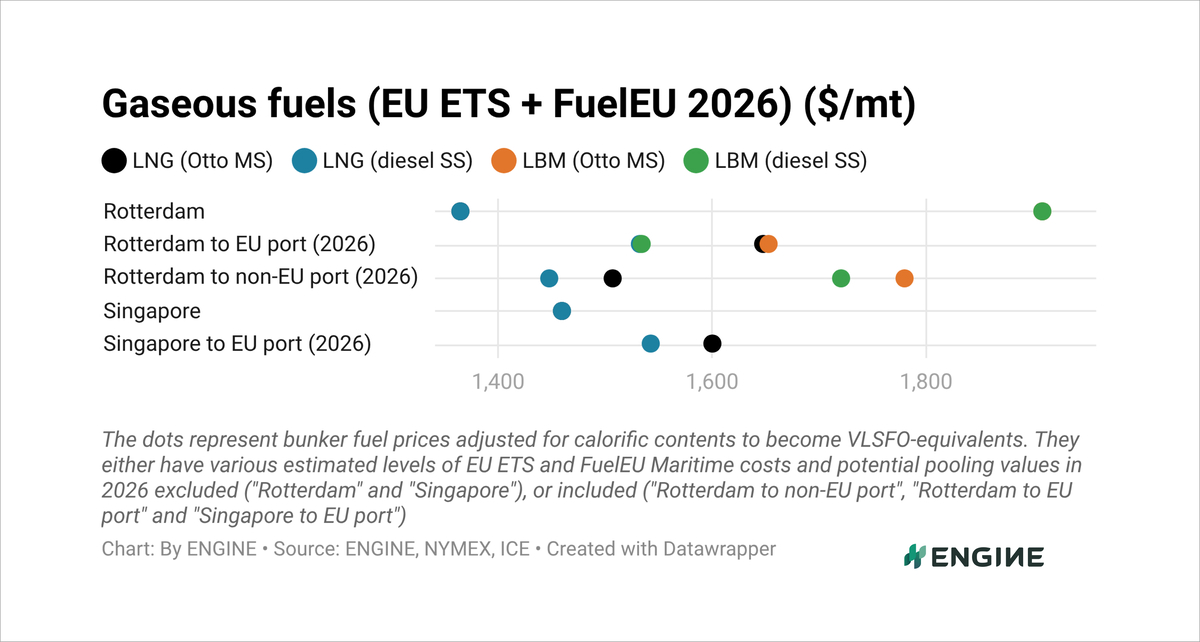 All bunker prices described in the text below have been adjusted for calorific content to make them VLSFO-equivalent. They have estimated EU-EU voyage compliance costs included for Rotterdam, and nonEU-EU compliance costs included for Singapore. These account for EU ETS costs and FuelEU Maritime penalties, and the average price of compliance surpluses we have picked up from the FuelEU pooling market over the past week.
Liquefied biomethane (LBM) is closing in on LSMGO in Rotterdam. Its discounts to LSMGO have narrowed by $100-103/mt to $17-137/mt, depending on engine type.
For dual-fuel vessels bunkering in Rotterdam, LBM costs more than HSFO, VLSFO and B100, irrespective of the vessel’s engine type.
LBM’s premiums over B100 have narrowed by $16-19/mt to $465-584/mt, as B100 has gained $54/mt and LBM $35-38/mt.
The ENGINE-assessed FuelEU Maritime pooling value has risen by €8.90/mtCO2e ($10/mtCO2e) to €95.80/mtCO2e ($108/mtCO2e) over the past week.
This has pushed the potential pooling value of LBM’s compliance surplus $31-36/mt higher in the past week. B100’s potential pooling value has also gained $30/mt in the past week.
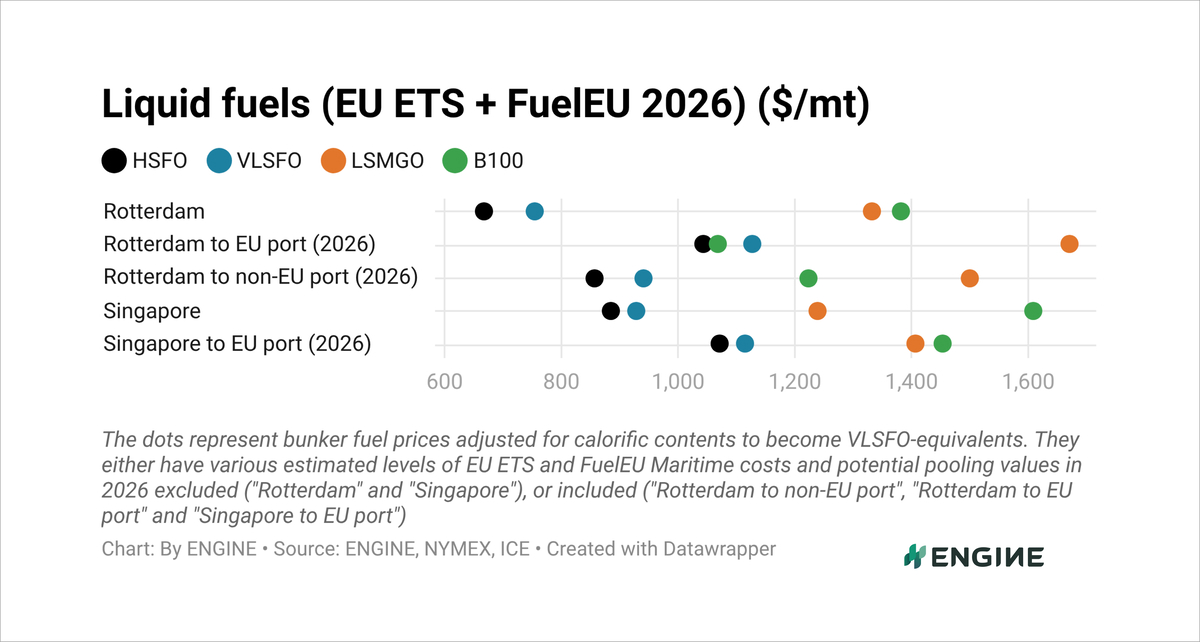
Rotterdam’s B100 has flipped from a $24/mt discount to HSFO to a $26/mt premium over it.
B100’s discount to VLSFO in Rotterdam has narrowed by $26/mt to $58/mt. Its discount to LSMGO has narrowed by $119/mt to $602/mt, as LSMGO has dropped by $65/mt and B100 has gained $54/mt.
Singapore’s B100 premium over VLSFO has narrowed by $1/mt to $337/mt. Its premium over LSMGO has widened by $15/mt to $44/mt.
Liquid fuels
Rotterdam’s HSFO and VLSFO prices have gained $4-28/mt over the past week, with VLSFO up the most. Its LSMGO has dropped by $65/mt.
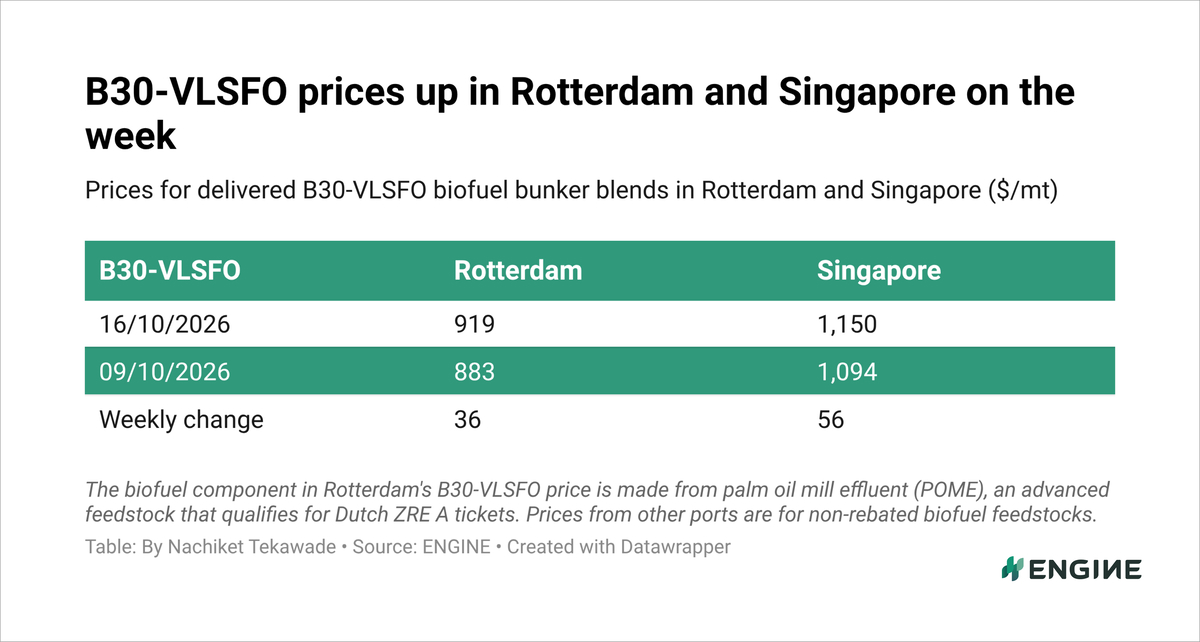
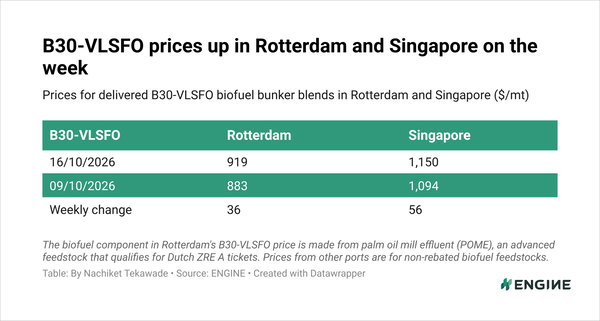
Rotterdam’s B100 has gained $54/mt, despite a $30/mt rise in its potential pooling value. B30-VLSFO has risen by $24/mt and B30-LSMGO has dipped by $2/mt in the past week.
Singapore’s conventional fuel prices have gained $8-61/mt over the past week, with HSFO up the most. Its B100 has risen by $23/mt.
Singapore’s bio-blended bunker sales rose sharply in September, increasing by 43% to 81,000 mt, which was the highest monthly volume since March. The port also recorded B100 bunker sales for a sixth consecutive month, with 2,600 mt sold in September, up from 800 mt in August.
Liquid gases
Rotterdam’s LNG prices have gained $72-75/mt over the past week depending on engine type. Its LBM prices have gained $35-38/mt.
For vessels with Otto medium speed (Otto MS) engines, LBM’s premium over LNG has narrowed by $37/mt to $5/mt. For vessels with diesel slow speed (diesel SS) engines, it has narrowed by $37/mt to $1/mt.
Rotterdam LBM’s premiums over VLSFO have widened by $7-10/mt to $407-526/mt.
Singapore’s LNG prices have risen by $144-146/mt depending on engine type, as the JKM contract they are priced on has moved from November to December delivery. That move accounts for $146/mt of the rise. Excluding it, LNG (Otto MS) has held level and LNG (diesel SS) has dipped by $1/mt.
In Singapore, LNG burnt in diesel SS engines has flipped from a $1/mt discount to LSMGO to a $136/mt premium over it. LNG burnt in Otto MS engines has widened its premium over LSMGO by $138/mt to $193/mt.
LNG’s premiums over VLSFO in Singapore have widened by $121-122/mt to $429-486/mt.
By Konica Bhatt
Please get in touch with comments or additional info to news@engine.online