Future Fuel Talks: Ammonia bunkering needs customers beyond early adopters – CMB.TECH
CMB.TECH’s fleet will generate initial demand for the Walvis Bay ammonia bunkering terminal, but third-party demand will underpin its commercial viability, Roy Campe told ENGINE.
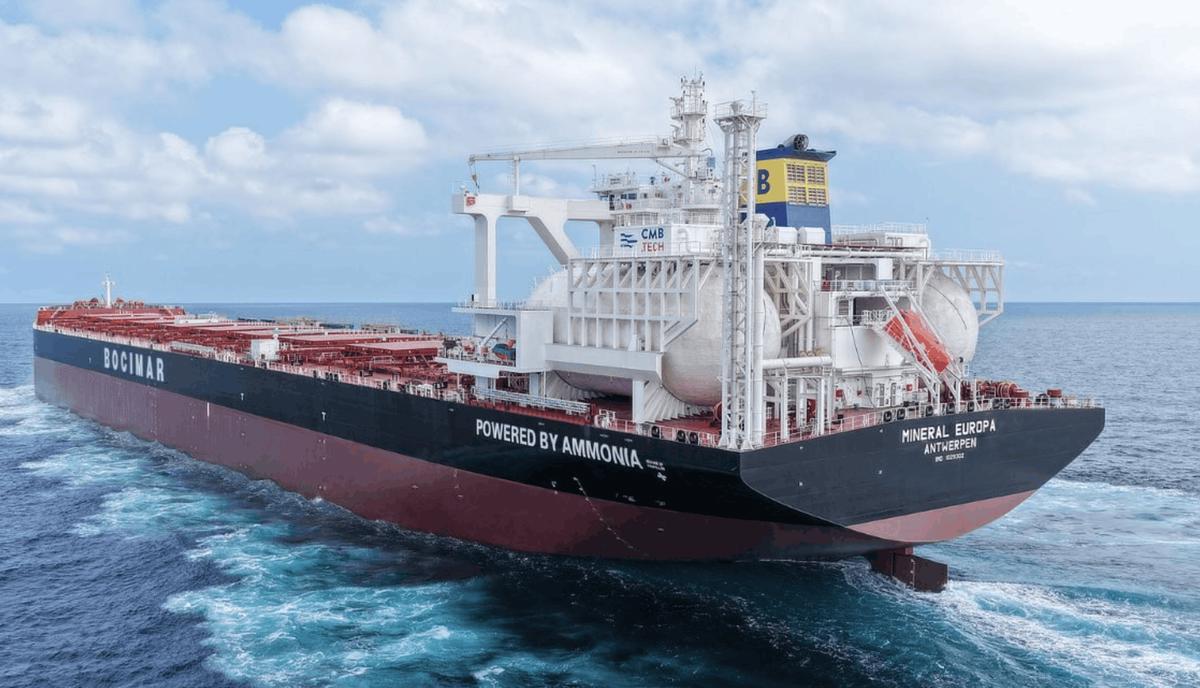 IMAGE: The ammonia-capable dry bulk carrier Mineral Europa. CMB.TECH
Campe is the chief technology officer at CMB.TECH, which plans to expand its ammonia-capable fleet to 21 vessels by 2029, comprising 18 bulk carriers, one container ship and two chemical tankers.
The first of these vessels, the Mineral Europa, has left the shipyard for Australia under charter to mining firm Fortescue. Several other vessels are due for delivery over the next nine months.
The Belgian shipping company has a longer-term ambition to expand its ammonia-capable fleet to over 40 vessels, although it has not specified a timeline for all of them.
CMB.TECH is also developing an ammonia bunker terminal in Namibia’s Walvis Bay, with plans to supply its own vessels as well as other shipowners, fuel producers and traders.
Construction of the terminal is scheduled to begin in 2027, with completion expected in late 2028 or early 2029. Ammonia will initially be imported from markets including Asia and North America and stored at the terminal before being supplied as bunker fuel to ships operating in the Atlantic Ocean.
In an exclusive interview with ENGINE, Campe explained that shipowners can hedge their ammonia investments through dual-fuel flexibility, but bunker infrastructure investors face “location-specific” commercial risks if demand takes longer than expected to materialise at individual ports.
Why did CMB.TECH choose Walvis Bay for its first ammonia bunkering infrastructure investment, given the limited number of ammonia-capable vessels currently on order?
CMB.TECH is developing an ammonia bunkering terminal in Walvis Bay to fuel its fleet of more than 40 ammonia-capable vessels. Namibia offers world-class solar resources, providing access to some of the cheapest renewable energy in the world, while Walvis Bay combines this energy potential with the strategic advantage of a deep-sea port with significant room for future expansion. This creates a strong foundation for the large-scale production, storage and bunkering of green ammonia.
By developing infrastructure, production capacity and maritime demand in parallel, CMB.TECH aims to accelerate the market and connect Namibia’s renewable energy potential with global maritime and industrial customers.
You have said Walvis Bay is intended to serve the wider ammonia market as well as CMB.TECH’s fleet. How important will third-party demand be to the commercial case for the terminal?
CMB.TECH’s fleet provides the initial demand, while third-party volumes from producers, traders and other shipping companies will be essential to scale the terminal and maximise utilisation. Our aim is to kick-start an open market, not build a closed ecosystem.
How will investing in ammonia bunkering infrastructure help CMB.TECH’s planned fleet of 40 ammonia-capable vessels manage the risks of adopting a new fuel?
Investing in both vessels and bunkering infrastructure addresses the industry’s chicken-and-egg problem. Our fleet creates initial fuel demand, while storage and bunkering investments support reliable supply, allowing both sides of the market to scale together.
How do the commercial risks differ between investing in ammonia-capable vessels and ammonia bunkering infrastructure, particularly outside the EU, where future demand and regulatory incentives remain uncertain?
The commercial risks are different in nature. Ammonia-capable vessels are long-term assets, and dual-fuel technology provides operational flexibility by allowing them to run on conventional fuels while the ammonia market develops. The main risk is therefore the pace at which ammonia becomes commercially competitive and widely available.
Bunkering infrastructure carries a more location-specific risk. Its profitability depends on sufficient throughput at a particular port, making it more exposed to uncertainty around local demand, regulation and the timing of market development. If demand develops more slowly than expected, the infrastructure may take longer to reach its intended utilisation.
However, we believe the long-term direction is clear: the pathway towards cost-competitive green molecules is becoming increasingly visible. Countries such as Namibia, with abundant land and exceptional renewable energy potential, are well positioned to produce clean energy at competitive prices. Combining this potential with a deep-sea port such as Walvis Bay, which offers room for expansion, creates a compelling long-term case for ammonia infrastructure.
These are long-term investments that need to be assessed over decades, rather than against today's market conditions alone. By aligning investment in vessels, production and bunkering infrastructure, CMB.TECH aims to help develop the market while managing the risks associated with its gradual emergence.
Would CMB.TECH consider investing in ammonia bunkering infrastructure at other ports if there is sufficient demand, either from its own fleet or the wider market?
Yes. CMB.TECH already has an off-take agreement with CEEC Hydrogen Energy in Jilin and holds a stake in Andefu [Jiangsu Andefu Energy Technology], one of China’s largest ammonia supply-chain companies. We will continue working with producers worldwide to secure fuel for our fleet.
[As part of its investment in Andefu, CMB.TECH signed a long-term agreement to purchase 20,000–25,000 mt of green ammonia in the first year from CEEC Hydrogen Energy’s production facility in China’s Jilin Province, with deliveries to be made through ship-to-ship transfers. The offtake volumes will increase to 40,000-50,000 mt in the second to fourth years.
The partnership also supports an ammonia terminal in Panjin, China, due to start operations in 2027, and the gas carrier Shenghang Yongle has been converted into an ammonia bunker vessel that entered into service last month.]
Ammonia bunkering projects are now emerging in select ports across Asia, Europe, the Middle East and Africa. Could the ammonia bunker market initially operate around a handful of strategic hubs, or will shipping need a wider global network before 2030?
Ammonia bunkering can initially develop around a limited number of strategic hubs, a fully global network is not needed for the first vessels. The priority before 2030 is safe, reliable supply at key ports on established trade routes. As the fleet grows, these hubs can expand into a broader global network.
What would you need to see from global shipping regulations to give early adopters and investors greater certainty about the future low- and zero-emission ammonia bunker market?
Early adopters need a clear, predictable global framework that closes the cost gap with fossil fuels. This should include lifecycle-based greenhouse-gas standards, a meaningful emissions price and consistent fuel certification. IMO-led rules would create a level playing field and give shipowners, producers and infrastructure investors the confidence to invest.
By Konica Bhatt
Please get in touch with comments or additional info to news@engine.online